

This article from The Contrarian Capitalist looks beyond crude oil headlines to examine the refined-product constraints now reshaping energy markets, geopolitics and inflation.
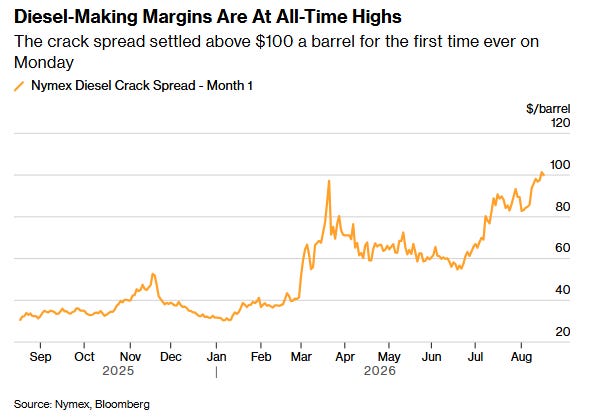
The U.S. diesel crack is hovering around $100 per barrel. This is not normal and signals refined-product bottleneck rather than a simple shortage of crude.
Global refining capacity losses, low European gas storage and rising power demand from AI and electrification are all adding pressure.
This tightness is pushing costs higher across farming, freight, travel and mining to name a few. This in turn is feeding an increasingly persistent inflation narrative.
In a commodity supercycle the same cost pressures that lift AISC also reinforce structural scarcity and the subsequent monetary conditions historically favour hard assets.
Elevated nominal yields do not stop gold from performing when real rates fall or liquidity expands.

Annual Subscription → Normally $110 → Now Just $55!
Lock in lifetime access to conviction-driven research, weekly commodity and market wraps, and high-conviction investment insights at 50% off.
This 50% discount applies to all annual subscriptions taken before Tuesday 8th September 2026, and once subscribed, your rate remains fixed for as long as you wish to remain a Contrarian Capitalist!
The Diesel Squeeze: What Refined-Product Tightness Means for the Real Economy and Hard Assets
Crude oil prices grab the headlines every day, yet the more important signal is happening further on down the chain.
On Monday 17th August 2026, the U.S. diesel crack spread (the premium of ultra-low sulfur diesel over West Texas Intermediate aka WTI), hit a high of $102.20.
The long-term normal range has been between $15 - $30, so moving and settling above $100 is a significant event.
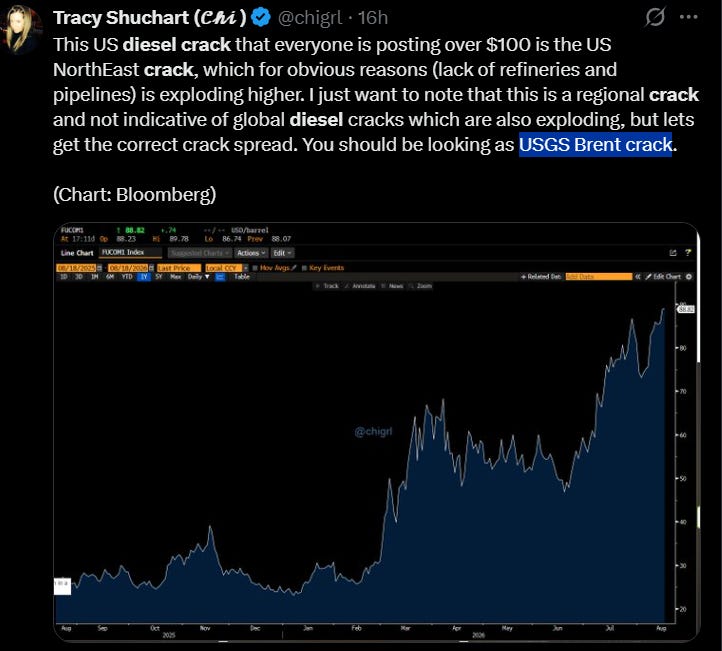
Tracy Shuchart made a fair point that the extreme reading from 17th August may have partly reflected the regional U.S. shortages of refining capacity and pipelines.
I’ve added the NYMEX Monthly chart below for good measure. This was inserted after market close on Monday 31st August 2026. It shows the crack spread futures at $99.98.
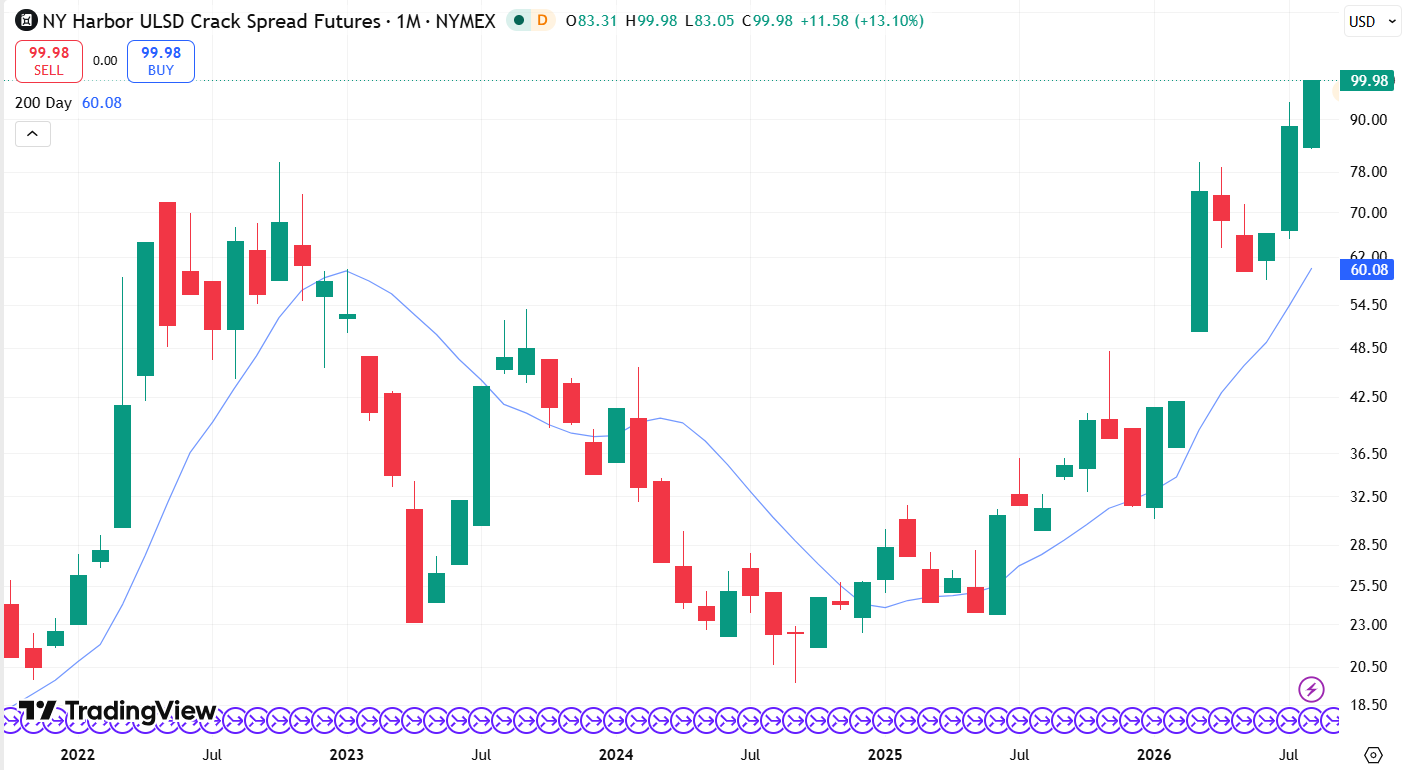
All that being said, the broader picture is pretty clear. Diesel cracks are elevated, the trend is still rising (look at the simple 200-day moving average on the chart above), and the market is flashing a big red warning.
First of all, what is a diesel crack spread?
A diesel crack spread is the profit margin refiners make by turning crude oil into diesel fuel.
Refineries buy crude oil (WTI, Brent etc) which is classed as the raw material, and then ‘‘crack’’ it down through refining, and out pops the usable products such as gasoline (petrol), diesel etc.
As mentioned above, the diesel crack spread therefore is the difference between the selling price of diesel and the cost of the crude oil.
It’s normally quoted in U.S. Dollars per barrel.
I.e. Diesel = $200
Crude = $100
Crack Spread = $100 because $200 - $100 = $100
The challenge with a higher spread is that diesel is the power of the real economy.
Diesel and inflation
Diesel is the economy. Think farming, airline industries, construction machinery, rail, shipping and most industrial activity to name a few. Higher crack spreads normally signal that diesel supplies are tight relative to demand, thus pushing up prices.
This then gets passed onto the producer, and ultimately the consumer. This is a critical contributor of the inflation process. From a Central Bank point of view, inflation becomes even more problematic if there are high diesel crack spreads.
4 potential key drivers include:
1) Geopolitical disruptions from conflicts i.e. refining capacity decreases and/or export bans
2) Very low inventories
3) Seasonal demand peaks (i.e. agricultural harvest).
4) Limited ability to quickly ramp up global refining capacity to replace lost barrels.
The last point is particularly salient as supply challenges are something that are often mentioned on The Contrarian Capitalist. You simply cannot magic up new refining capacity overnight.
The nature of the constraint
Diesel and middle distillates power the machinery of the real economy. Unlike gasoline, diesel demand is deeply embedded in production and logistics and is less price-elastic in the short run.
U.S. distillate inventories (diesel plus heating oil) were around 107 million barrels in early August. This is the lowest for this time of year since 1996. Refineries are already running hard and exporting large volumes, yet stocks are not rebuilding.
As per point 1 above, global refining capacities have been severely disrupted by ongoing conflicts such as between Russia & Ukraine and also in the Middle East.
China has the largest pool of spare capacity in the world, but export quotas have limited how much of that capacity actually reaches the global market. The result is a structural bottleneck in refined products.
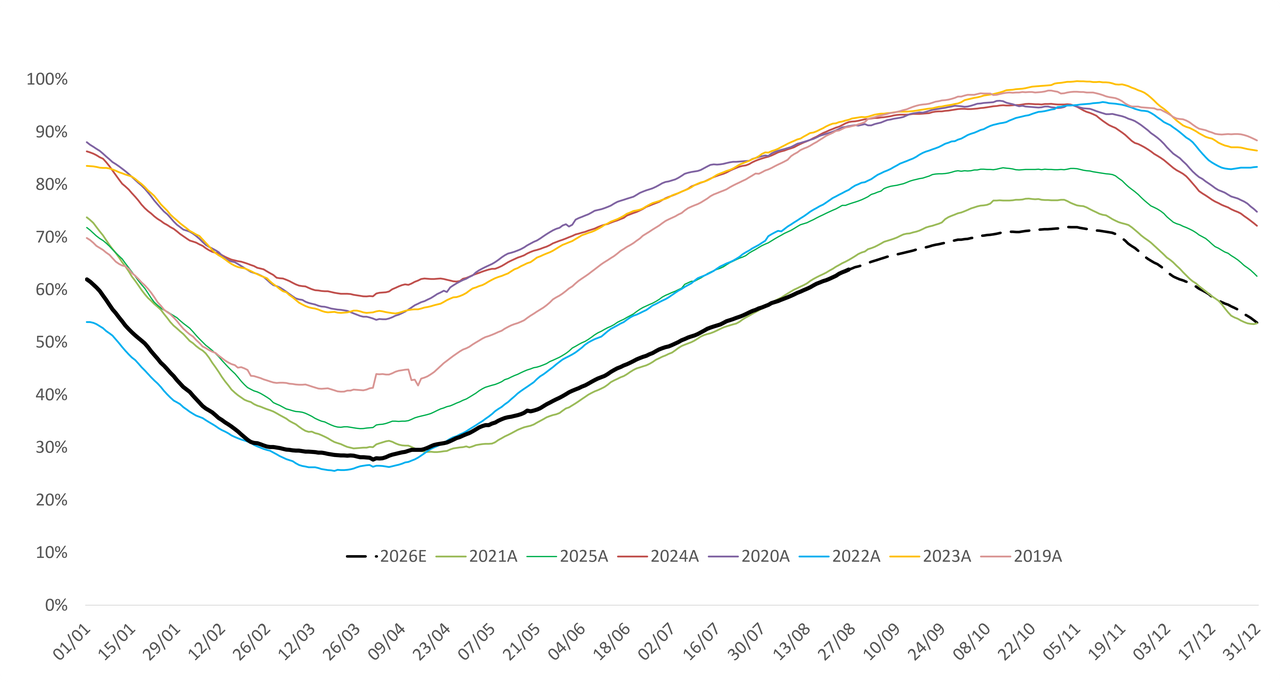
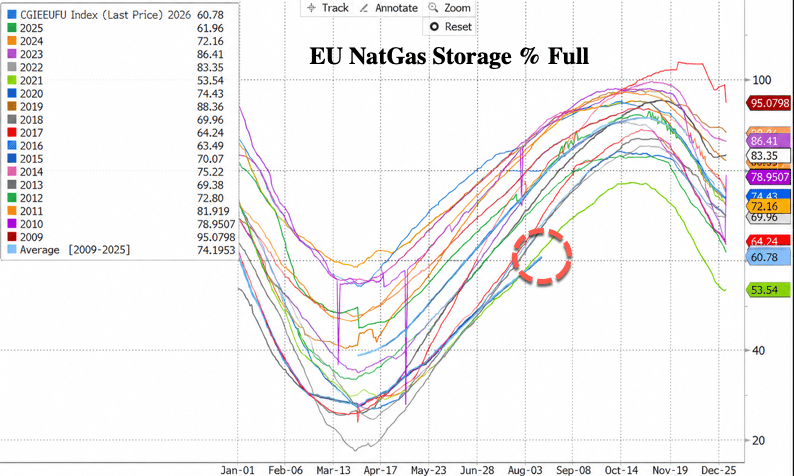
It is not just diesel where there are growing concerns. Europe is showing a parallel problem (albeit self-induced) in Natural Gas. EU natural-gas storage stood near 63% full in late August, which is well below normal levels for this time of year.
The two charts below from GIE AGSI. 2026E estimate = Asymmetric Research and ZeroHedge help to highlight this.
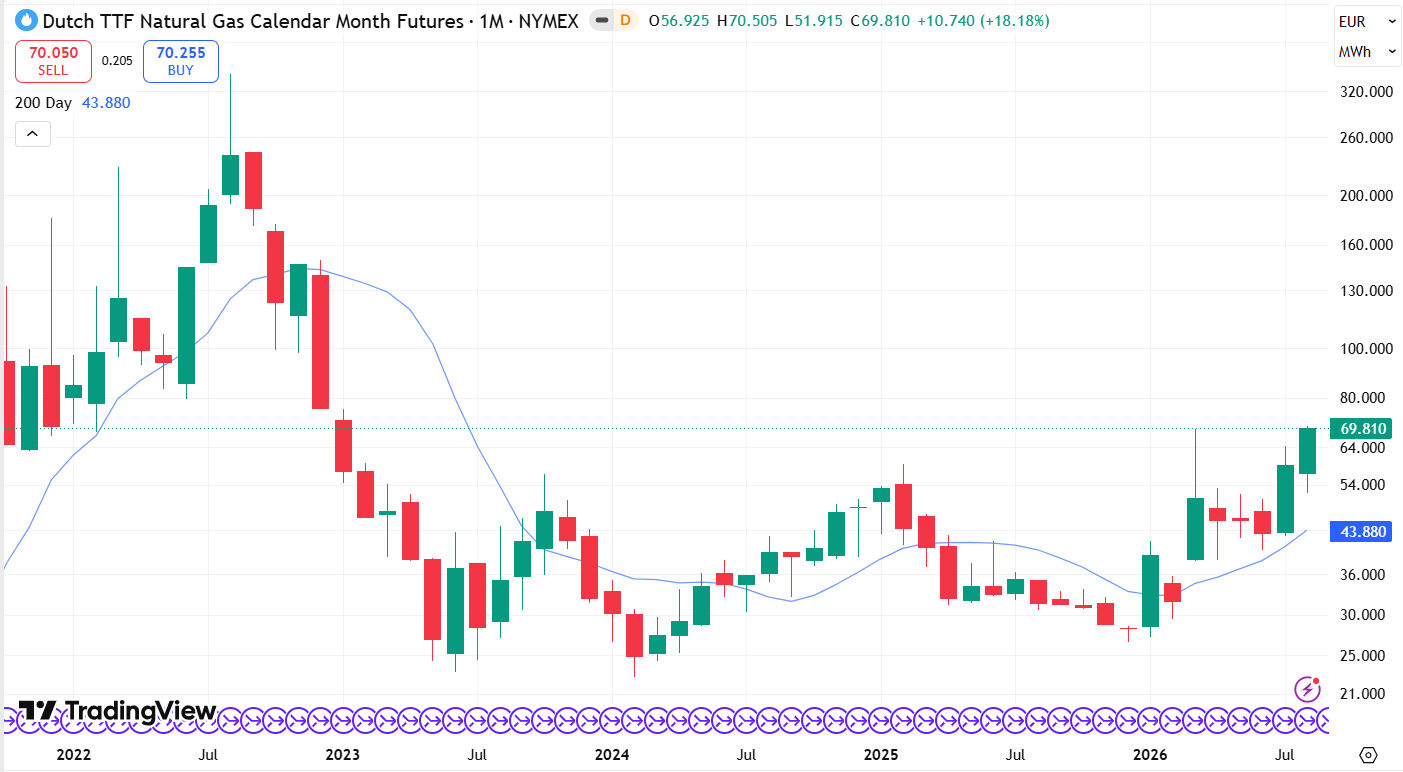
This is also reflected in increasing Dutch TTF Futures Prices. Monthly chart below.
Add rising electricity demand from AI data centres and broader electrification, and the pressure on the whole energy system increases. Diesel becomes even more important for backup power and remote operations.
The recent long-term U.S.–Venezuela oil arrangement may eventually help on the crude side, but it will take years to deliver meaningful extra supply and will not solve the refining bottleneck in the near term.
How the squeeze reaches the real economy - Mining, Food and Transport
In mining, diesel is a core operating cost. For many open-pit operations it routinely accounts for 15 - 25% of all-in sustaining costs (AISC). Higher diesel prices increase the cost of transport, drilling, power and explosives. Several companies have already raised AISC guidance.
In a supercycle environment this is actually less damaging than it sounds. Higher costs can make new projects harder to justify and stretch already long lead times, but historically speaking, rising metals prices are more than likely going to offset higher AISC.
The same diesel pressure hits agriculture and transport. It is the main fuel for planting, harvesting and moving food. Combined with weather and climate pressures, this has already shown up in soft commodities.
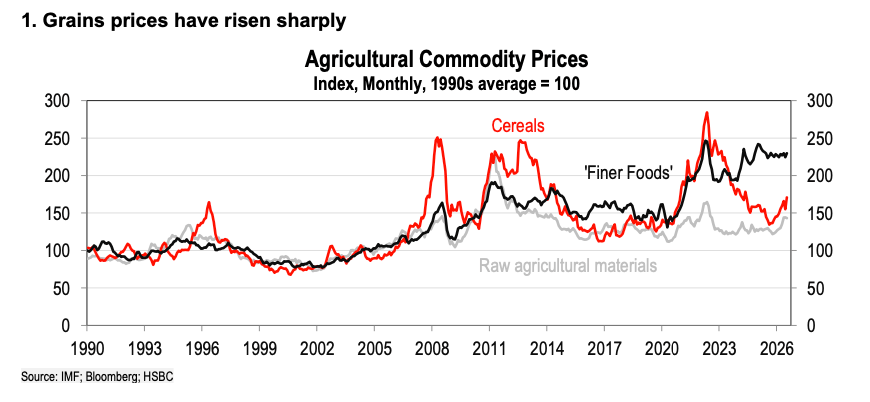
According to Bloomberg, cereal prices, including wheat, corn, barley, and rice have risen 22% year over year through to July 2026.
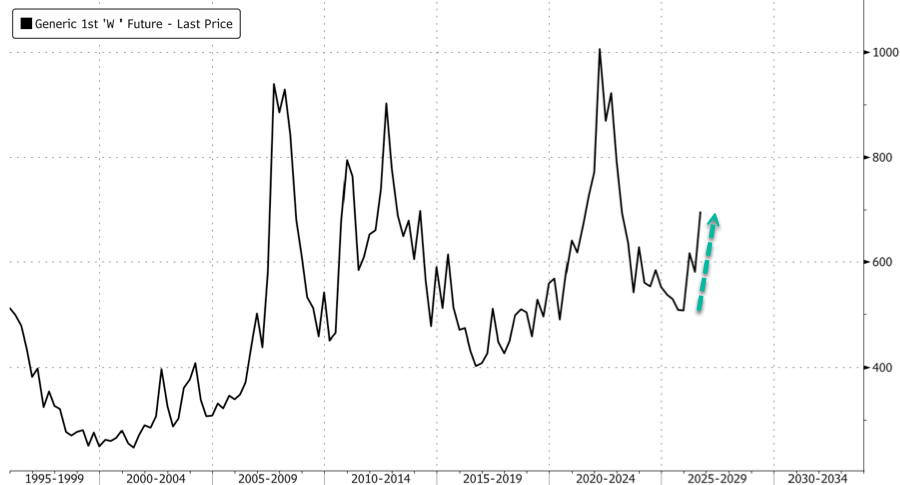
Wheat Prices actually hit a 3 year high in August (graph annotations from ZeroHedge)
Sugar prices have jumped approximately 40% in a matter of months. This prompted the Indian government to import over 1 million tonnes. India is the highest consumer of sugar in the world.
It’s not just diesel that will have an impact on soft commodities, but also the weather/general climate too.
With an abundance of conveniently located forest and wildfires that have cropped up (pun intentional) in the last number of years, surrounding arable land has been affected.
Add to that an ‘unprecedented’ El Niño, and we likely have a recipe for disaster in the years ahead. Too dry and this will damage crop yields. Too wet and this will also damage crop yields. Too cold and this will also damage crop yields. The end result will be the same.
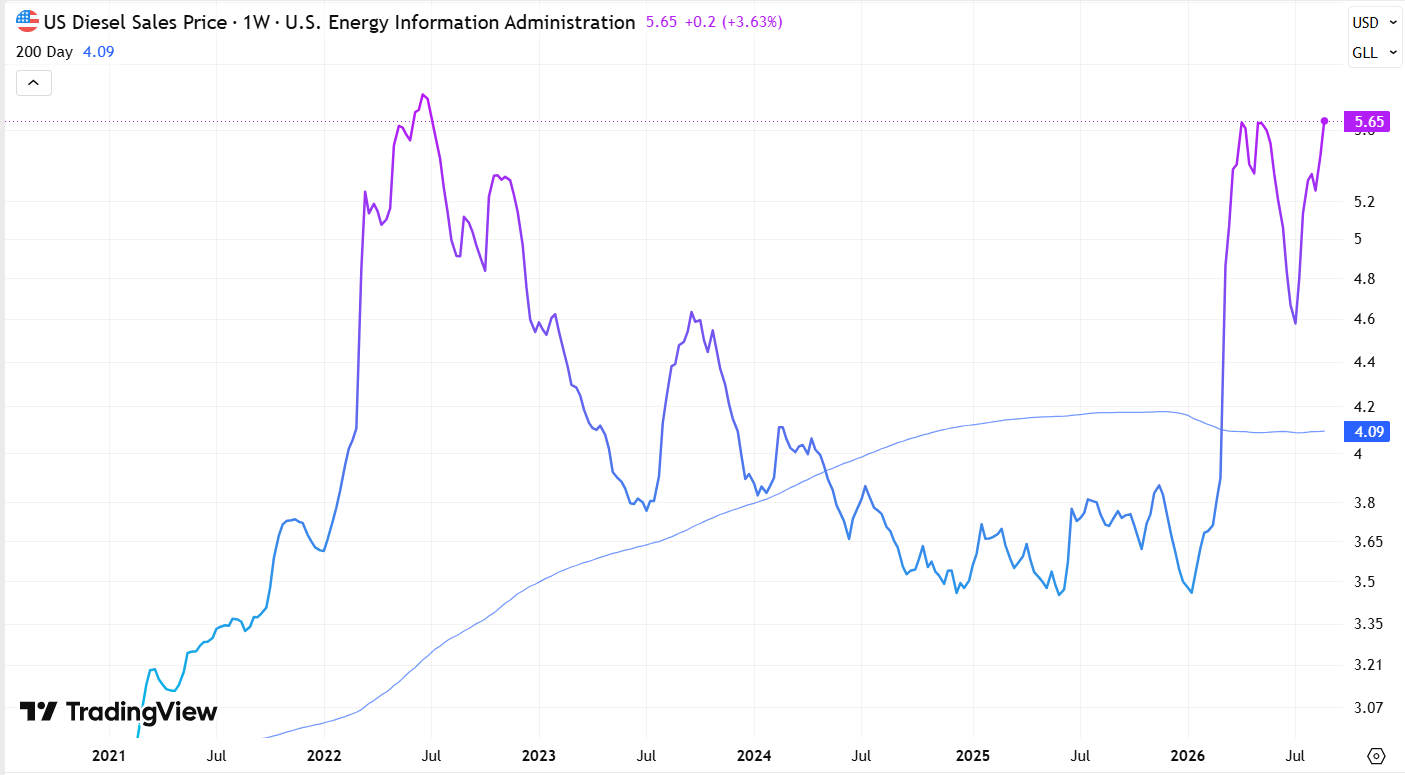
With regards to diesel at the pump, we can see that in the U.S. the sale price is back over $5 per-gallon. Even if crude itself softens, a wide crack spread can keep the inflationary impulse alive in the physical economy. This is why we should take CPI/PPI/PCE figures with a pinch of salt.
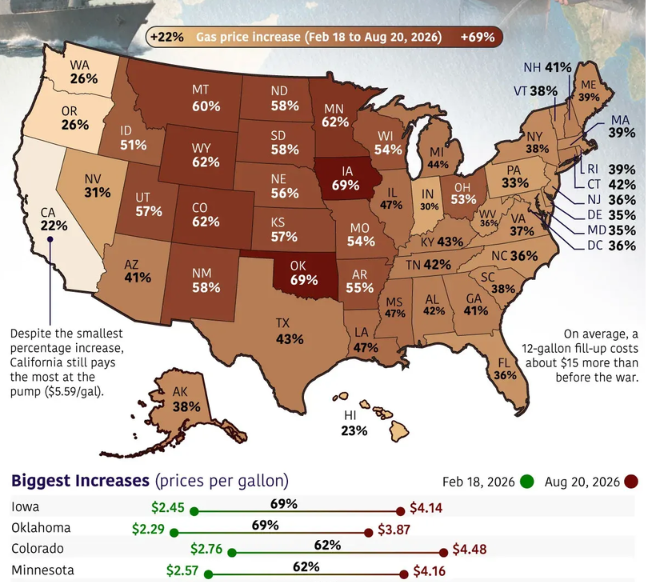
The picture isn’t much better for gasoline in the U.S. either. Graph courtesy of VBL
Geopolitical and monetary implications
What we are seeing is classic cost-push inflation i.e. higher input costs rather than excess demand.
It therefore becomes very difficult conventional monetary tools to address this. Central Banks could try to raise rates and cool demand, but they ultimately cannot refine more diesel or rebuild inventories by decree.
NB - I do not think that the Fed will raise rates in September or October. The best thing they can do at the moment is to do nothing.
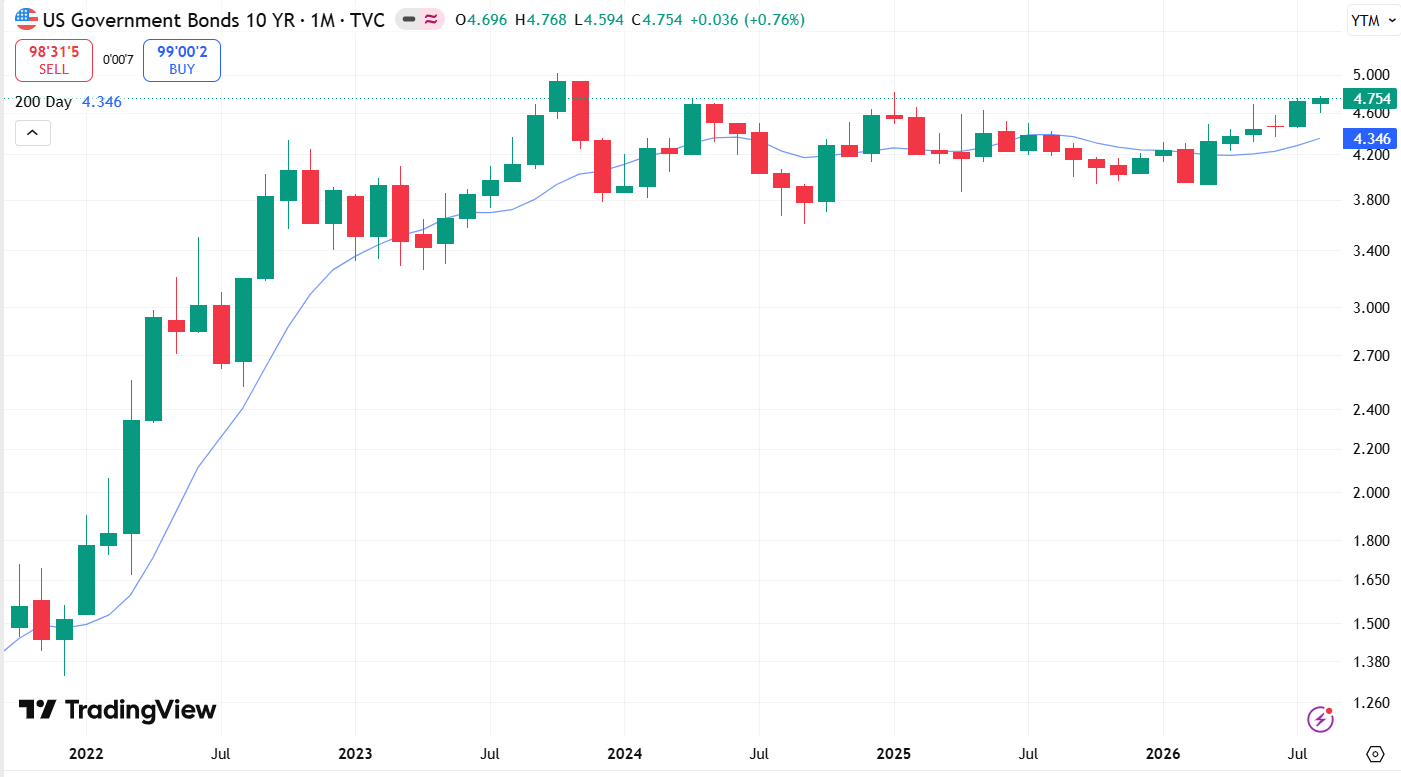
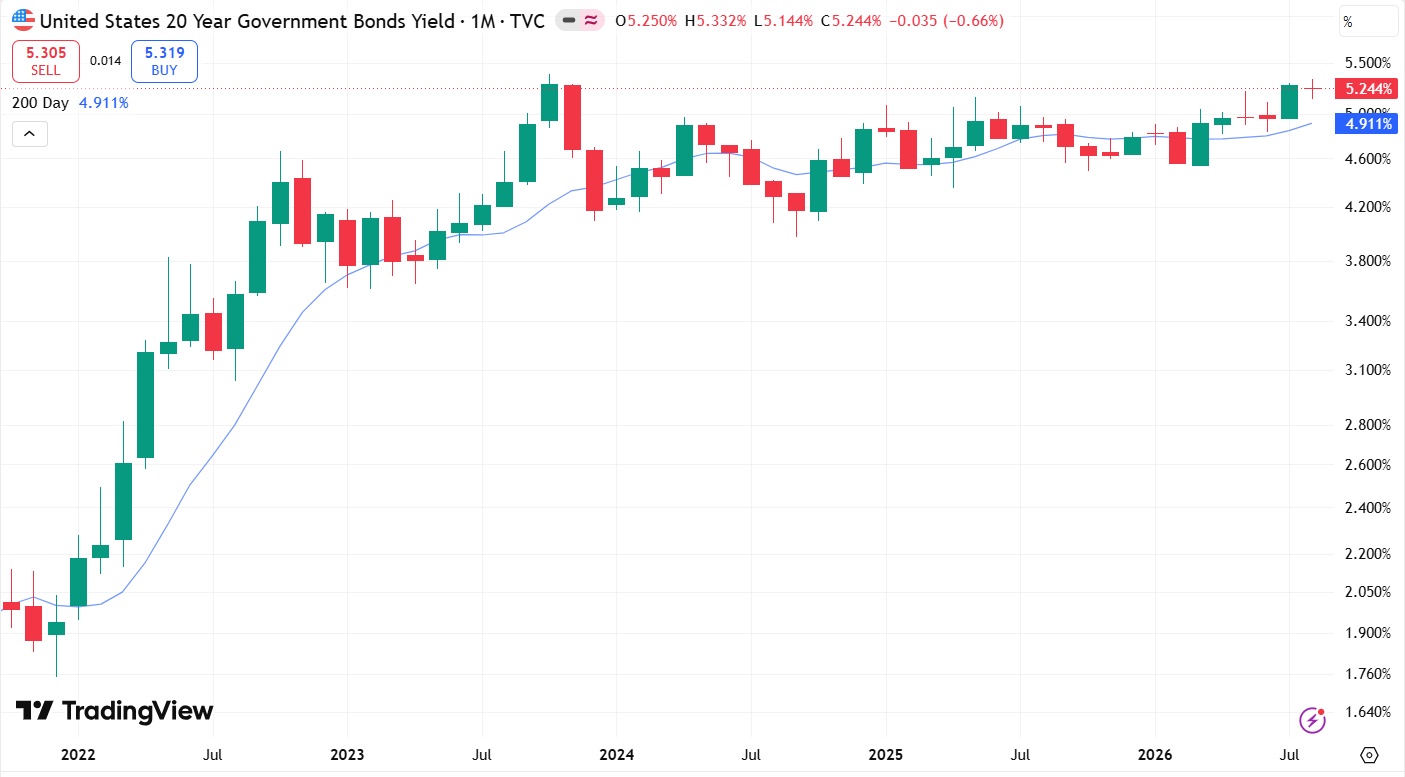
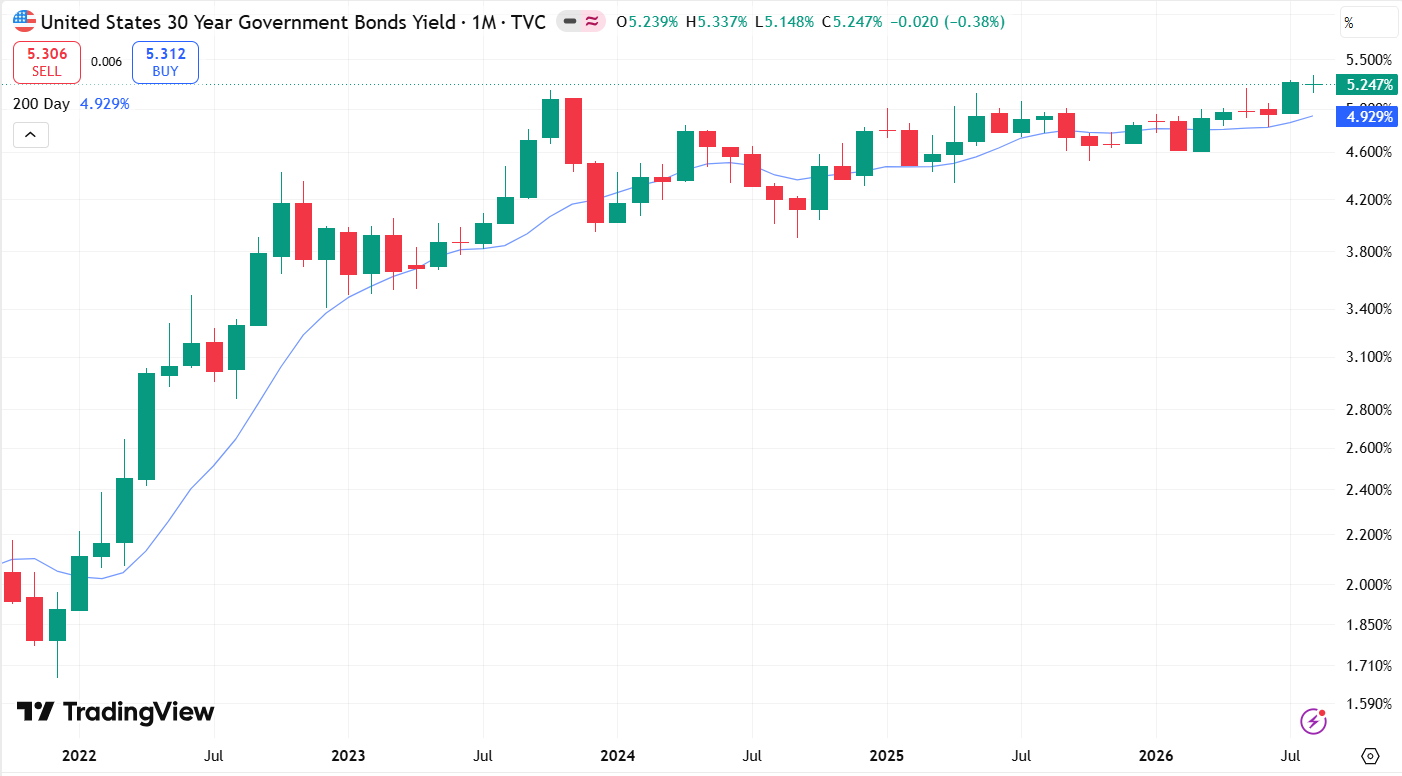
Bond yields are continuing to grind higher. This reflects the recent inflation and ongoing fiscal pressures. Further cost-push inflation from energy and logistics can (and will) keep nominal yields higher for longer, thus aligning with the idea that the Fed will have to run the economy hot as it is the only viable and politically palatable option that they have left.
NB - The other options being to increase taxes, reduce spending or to default.
The US 10, 20 and 30 year bond yield monthly charts below were inserted after market close on Monday 31st August 2026.
10 Year
20 Year
30 Year
If governments and central banks worldwide decide to run their economies hot, then this will work well for gold. Persistent supply-driven inflation combined with financial stress and general fiscal pressures will increase the probability of QE.
More currency printing, balance-sheet expansion and any other forms of liquidity support will be good for gold and friends.
This is because the above responses help to accelerate the longer-term process of currency debasement. In such an environment, even elevated bond yields do not prevent gold from performing if real yields fall or if more and more people became aware and seek protection against eroding currencies.
These forces feed one another in a commodity supercycle. Physical scarcity supports higher metals prices. Higher prices keeps inflation sticky. Sticky inflation increases the chance of monetary responses that subsequently favour real assets.
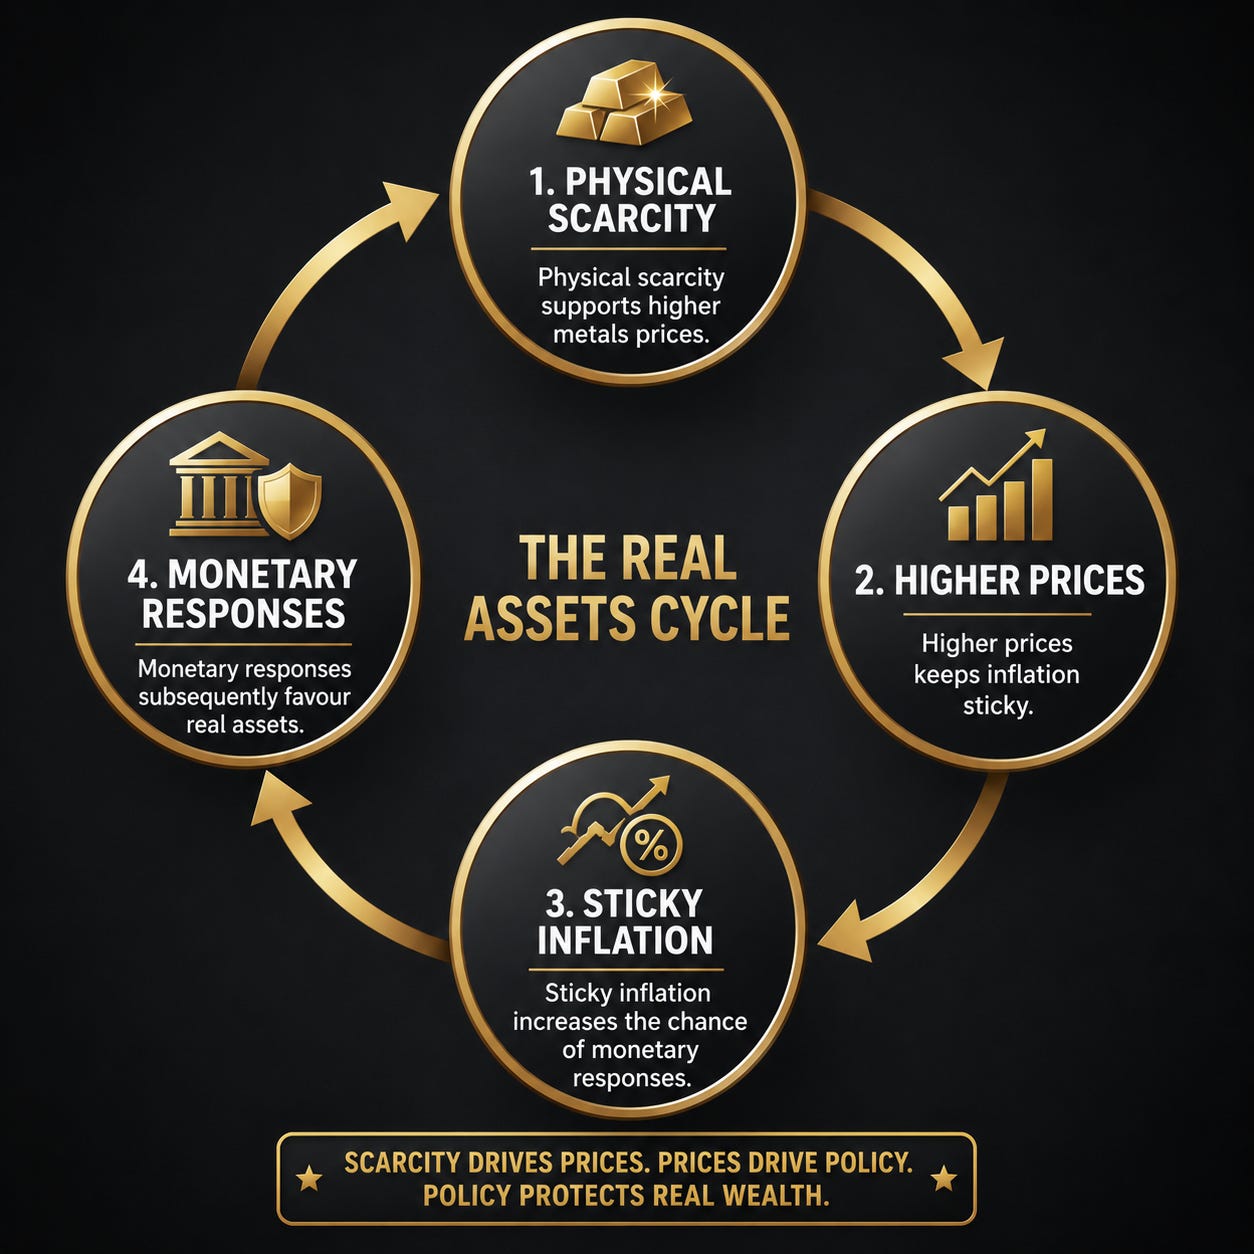
NB - ChatGPT created the above image.
Years of underinvestment in both refining and mining capacity, combined with structural demand growth from electrification and AI, makes the current tightness more than a short-term disruption.
If diesel crack spreads remain higher for longer, the more severe the consequences for the masses but so too the better the opportunities become.
The investment backdrop and action points
Please note that none of the following is designed as investment advice. Please always do your own homework and speak to the relevant professionals.
The 30,000ft view is quite simple as we are in for an overall period of:
Higher commodity prices as part of a commodity supercycle and supply/demand imbalances
Higher Inflation
Quantitative Easing and/or broadening monetary accommodation
Continued Debasement of Fiat Currencies
Using the above as the overall thesis, then your playbook should be along the lines of:
Clear bad debt
Watch the diesel crack spread closely
Hold physical gold and silver as insurance against inflation and currency debasement
Keep at least 6 months of cash or liquid reserves (see point above)
Favour well-capitalised commodity producers in areas where there are genuine supply constraints and where rising prices can more than offset higher AISC
Avoid assuming that high bond yields will restrict gold. They won’t
Have a Plan B in place i.e. second residency and/or passport
The diesel market is flashing a clear warning. The consequences are starting to be felt across the real economy and will continue to be felt moving forwards.
Positioning properly for the monetary and commodity response that usually follows will likely serve both you and your family very well in the years ahead.
Annual Subscription → Normally $110 → Now Just $55!
Lock in lifetime access to conviction-driven research, weekly commodity and market wraps, and high-conviction investment insights at 50% off.
This 50% discount applies to all annual subscriptions taken before Tuesday 8th September 2026, and once subscribed, your rate remains fixed for as long as you wish to remain a Contrarian Capitalist!
The Fed just declared an emergency demand whereby inflation must stay below 2% and interest rates must return to 1%. After all, they are the Gods of the universe.
You’re spraying bullets all over, while missing a relatively simple solution to the problem. Diesel (and, for that matter, jet fuel) rely on heavy, sour crude, which the US does not produce. The big producers are the Gulf States (throttled by the war against Iran) Venezuela (which will require $billions, and years, to bring back online), and Canada! Guess who has one of the world’s largest reserves of heavy crude? It wasn’t Trump who shut down the Keystone XL pipeline extension to Alberta, it was Biden, on his first day in office. Trump is not without blame - he could have reversed that decision, but he is trying to use it as leverage, in the ongoing (but temporarily-halted) US-Canada Trade negotiations. As much as I detest Mark Carney, he’s far smarter than Trump. He walked out of the negotiations because he knows “he has the cards”. The master of “The Art of the Deal” has been out-negotiated.
Without diesel and jet fuel, not only does the economy suffer, but the military grinds to a halt.